They Sound Interchangeable Until You Look Closer
Walk into a conference room at a major bank and you might hear the phrase "private banking" used as if it were synonymous with wealth management. Walk into an independent advisory firm and you
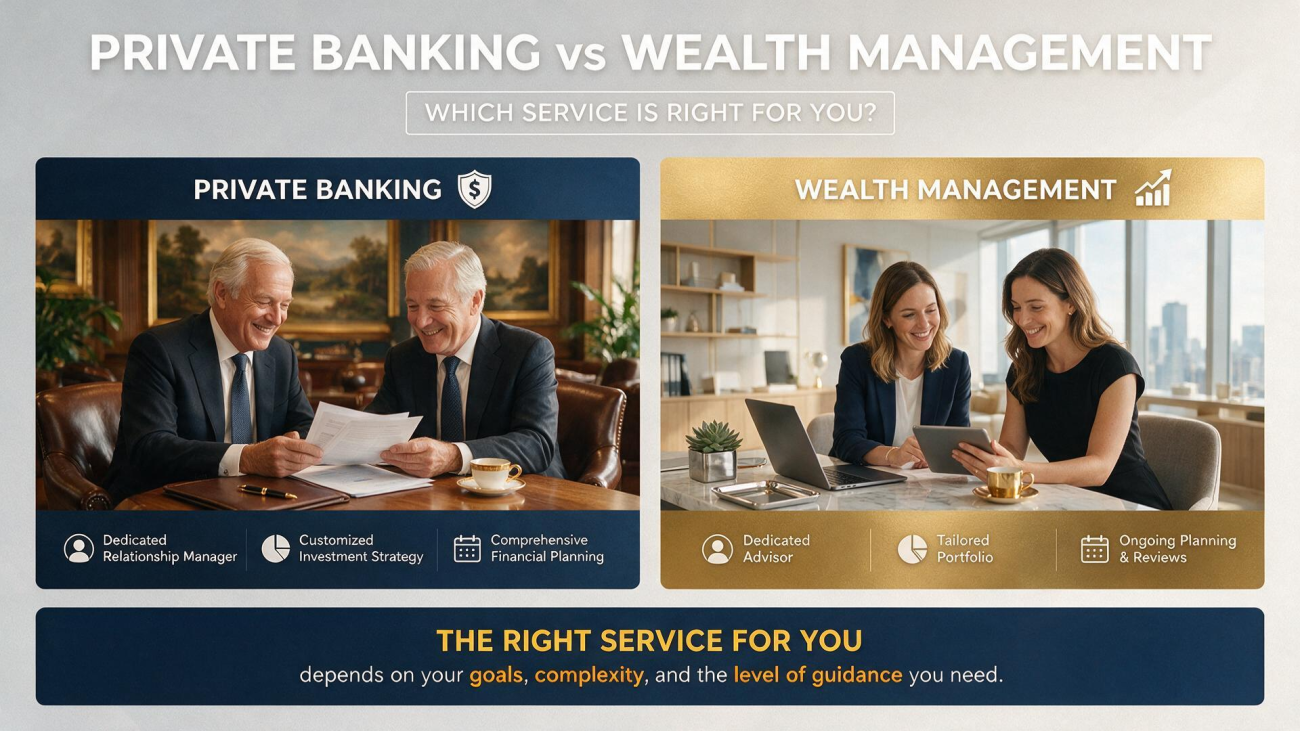
might hear the opposite. The confusion is understandable, because the two services overlap significantly and the industry itself doesn't always draw clear lines between them. But the differences are real, and they matter enormously for anyone trying to decide where to take their money. The private banking vs wealth management comparison isn't about which one is better in the abstract. It's about which one fits your actual situation, your actual needs, and the way you actually want to be served.The simplest way to frame the distinction is this: private banking is a service model within a bank, while wealth management is a broader discipline that can be offered by banks, independent firms, or a combination of both. A private bank is a division
of a financial institution that provides personalized banking, lending, and investment services to high-net-worth clients. Wealth management is the holistic process of coordinating all aspects of a client's financial life, including investments, tax planning, estate strategy, and more. One is a place you go; the other is a thing you do. The private banking services that work for you are the ones that fit your need for banking integration, while the wealth management solutions that work are the ones that fit your need for comprehensive planning.What makes this particularly relevant is that the two services are converging. Banks are building out their wealth management capabilities, and independent firms are adding banking-like services through partnerships. The lines are blurrier than they used to be, which means the decision isn't as simple as choosing a category. It's about understanding what each model does well, what it doesn't do well, and which one aligns with the complexity of your financial life.
What Private Banking Actually Does
Private banking is built around the idea that high-net-worth clients need more than a standard checking account. A private bank provides a dedicated relationship manager who serves as your point of contact for a range of services: deposit accounts with favorable terms, lending solutions including mortgages and securities-based lines of credit, foreign exchange, and investment management. The relationship manager coordinates across the bank's various departments, so you don't have to call five different numbers to get something done .
The lending capability is often the most valuable part of private banking. High-net-worth clients frequently have complex borrowing needs that standard banks can't accommodate. A securities-based line of credit lets you borrow against your investment portfolio without selling assets, which can be a tax-efficient way to access liquidity. A jumbo mortgage for a property that exceeds conforming loan limits requires a lender that understands complex income structures. A business owner who needs a credit facility tied to their company's cash flow needs a banker who can underwrite that kind of risk. The private banking benefits that matter most are often the ones that come from having a banker who understands your entire financial picture and can structure solutions accordingly.
The banking integration is another advantage. When your deposit accounts, your lending, your investment accounts, and your estate planning are all under one roof, there's a level of coordination that's hard to replicate with separate providers. Your banker can see your full relationship and make decisions accordingly. That can mean better terms on a loan, faster approvals, and a more seamless experience. The high net worth banking model is built on that integration, and for clients whose financial lives are intertwined with their banking relationships, it can be genuinely valuable.
The limitations are equally important to understand. Private banks are banks, which means they're subject to the same regulatory constraints and institutional pressures as any other bank. They have products they want to sell, and their advisors may have incentives that aren't perfectly aligned with your interests. Some private banks operate under a suitability standard rather than a fiduciary standard, which means they're not legally obligated to put your interests first at all times. The private banking services that serve clients well are the ones where the bank is transparent about those conflicts and manages them carefully.
What Wealth Management Actually Does
Wealth management is a broader discipline, and its scope is defined by the client's needs rather than the institution's product shelf. A good wealth manager coordinates investment management, tax planning, estate planning, retirement planning, insurance analysis, and often philanthropic and family governance advice. The goal isn't just to manage money. It's to create a coherent plan that addresses all the financial issues a high-net-worth family faces .
The fiduciary standard is often the defining feature of independent wealth management. Fee-only firms, in particular, are structured to avoid the conflicts that come from commissions and proprietary products. Their incentive is to grow your assets, not to sell you something. That alignment matters enormously over time, because the difference between a fiduciary and a salesperson can show up in the fees you pay, the products you're placed in, and the recommendations you receive. The wealth management solutions that work for high-net-worth clients are the ones where the advisor's interests are aligned with yours, and fiduciary status is the clearest signal of that alignment.
The depth of planning is another distinguishing feature. A wealth manager who specializes in high-net-worth clients can coordinate with your estate attorney, your CPA, and your insurance broker to make sure all the pieces of your financial life are working together. They can model different scenarios, identify tax-saving opportunities, and help you make decisions about complex issues like business succession, charitable giving, and multi-generational wealth transfer. The private banking vs wealth management distinction often comes down to this depth of planning. Private banking is broader in banking services but often shallower in planning; wealth management is narrower in banking but deeper in planning.
The limitations of wealth management are mostly about what it doesn't do. An independent wealth manager typically doesn't offer banking services directly. If you need a mortgage, a line of credit, or a foreign exchange transaction, you'll likely be referred to a partner institution. That's not necessarily a problem, but it means you're dealing with more than one provider and the coordination isn't as seamless as it would be within a single bank. The private banking benefits of integration are precisely what independent wealth management lacks.
Which Model Fits Your Situation
The choice between private banking and wealth management depends on what you need more: banking integration or planning depth. If your financial life is closely tied to banking services—you need complex lending, you have significant deposits, you want a single relationship manager for everything—a private bank may be the better fit. If your needs are more focused on investment management, tax planning, estate coordination, and long-term wealth strategy, an independent wealth management firm may serve you better .
For many high-net-worth families, the answer is both. They use a private bank for their banking and lending needs, and they use an independent wealth manager for their investment and planning needs. That approach gives them the best of both models, though it requires more coordination on their part and more diligence in making sure the two providers are aligned. The high net worth banking relationship can handle the day-to-day financial transactions, while the wealth manager handles the strategic decisions.
It's also worth considering the size of your assets. Below a certain threshold—often $1 million to $5 million, depending on the institution—private banking services may not be available or may not be worth the cost. Wealth management firms typically have lower minimums, though the best ones still focus on clients with substantial assets. The private banking services that are worth paying for are the ones that provide access to lending and banking capabilities you can't easily get elsewhere. If you don't need those capabilities, the value proposition is weaker.
The other factor is complexity. If your financial life is relatively simple—a portfolio, a home, a retirement account—you may not need the full breadth of either service. A good independent advisor can handle your investment management and basic planning without the overhead of a private bank or a full wealth management engagement. But if your life is complex—a business, multiple properties, international assets, a blended family, a desire to leave a legacy—the depth and coordination that a good wealth manager provides becomes much more valuable. The wealth management solutions that work are the ones that match the complexity of your situation.
Questions to Ask Before You Choose
Whatever model you're considering, there are questions that should be answered before you commit. The first is about fiduciary status. Are they a fiduciary at all times, for all services? If the answer is anything other than an unequivocal yes, that's a problem. The second is about fees. What's the total cost of the relationship, including advisory fees, product fees, and any banking charges? The third is about coordination. How do they work with other professionals, like your attorney and CPA? The private banking vs wealth management decision should be informed by the answers to those questions, not just by the brand name on the door.
It's also worth asking about the team. Who will actually be working on your account, and what's their experience with situations like yours? A private bank might assign you a relationship manager who's backed by a team of specialists, or you might be working with a single banker who's stretched thin. A wealth management firm might have a dedicated team for your account, or you might be one of many clients assigned to a junior advisor. The private banking benefits and the wealth management solutions both depend on the quality of the people delivering them, not just the institution's capabilities.
Finally, ask about the exit strategy. If you decide to leave, how easy is it to move your assets? Are there proprietary products that would need to be liquidated? Are there any surrender charges or exit fees? The best firms make it easy for you to leave, because they're confident you won't want to. The ones that make it hard are telling you something about their business model and their confidence in their own value.
Making the Decision
The private banking vs wealth management decision isn't a permanent one. As your needs change, the right model may change with them. A family that starts with a private bank for its lending needs might later add a wealth manager for planning. A family that starts with a wealth manager might later need private banking services as its assets grow. The high net worth banking landscape is evolving, and the lines between the two models are blurring, which means the decision is less about choosing a category and more about choosing the specific people and services that fit your situation.
The best approach is to interview both types of providers, ask the same questions, and compare the answers. Look for transparency, expertise, and a genuine understanding of your situation. Don't be swayed by the prestige of a brand or the polish of a presentation. The private banking services or wealth management solutions that work for you are the ones that fit your actual needs, not the ones that look most impressive on paper.
And remember that the relationship matters as much as the model. A private banker who understands your business, or a wealth manager who knows your family's history, can be worth more than a theoretically superior model delivered by someone who doesn't get you. The private banking vs wealth management choice is ultimately a personal one, and the right answer is the one that lets you sleep at night, knowing your wealth is being managed by people who have your interests at heart.
