Private banking has always carried a certain mystique. The mahogany-paneled offices, the relationship manager who knows your family by name, the sense that your money is being handled by people who genuinely understand what it means to preserve wealth
across generations. That world still exists, but it's being rebuilt from the inside out. The forces reshaping it aren't marquee names or grand strategy decks—they're quieter. They're the platforms your bank uses behind the scenes, the apps your children expect to work as smoothly as their favorite retailer's checkout, and the quiet expectation that a wire transfer shouldn't take three phone calls and a fax. The transformation is already well underway, and it's changing what private banking actually means.Why the Old Model Is Under Pressure
For decades, private banking ran on relationships and inertia. If your family had been with a bank for three generations, you stayed.
The service was personal, the advice was bespoke, and the technology—such as it was—remained safely in the background. Nobody chose a private bank because of its app. They chose it because their father had chosen it, or because a trusted advisor recommended it, or because the bank had a particular expertise in the family's industry or geography.That model is still alive, but it's straining. A new generation of wealth holders—many of them first-generation entrepreneurs, tech founders, and inheritors who grew up digital—expects a different experience. They want to see their positions in real time, not wait for a quarterly statement. They want to move money between accounts without calling anyone. They want to understand their exposure to a sector before it becomes a problem. And they want all of this to work on the same phone they use to book dinner reservations. The digital banking platforms that private banks are now deploying are the industry's answer to that expectation, and the ones that get it right are pulling ahead of competitors still clinging to the old ways.
There's also a competitive threat that didn't exist a generation ago. Digital-first wealth managers, robo-advisors, and fintech challengers have spent the last decade proving that sophisticated investment management doesn't require a marble lobby. They've captured younger clients and, increasingly, the children of traditional private banking clients. The incumbents have noticed. The question is no longer whether private banks will digitize, but how quickly and how well they can do it without losing the human touch that made them valuable in the first place.
The regulatory environment adds its own pressure. Know-your-customer rules, anti-money-laundering requirements, and cross-border compliance obligations have become more demanding, not less. A private bank serving clients with assets in multiple jurisdictions has to verify identity, monitor transactions, and document decisions at a scale that manual processes simply can't handle. Good technology isn't just a client convenience—it's a compliance necessity. The banks that haven't invested are finding that out the hard way.
What Modern Platforms Actually Deliver
The best private digital banking experiences don't look like consumer banking apps with a higher account minimum. They're built around the specific needs of clients with complex financial lives. That means consolidated reporting across dozens of accounts, entities, and jurisdictions. It means real-time visibility into cash positions and liquidity. It means the ability to execute transactions—wires, trades, transfers—without a phone call or a signature. And it means that all of this works reliably, because a private banking client who can't access their account at a critical moment is a client who starts looking elsewhere.
Consolidated reporting is probably the most underrated feature. A typical high-net-worth family might hold assets across multiple brokerages, a trust company, a private equity fund, a real estate partnership, and several bank accounts in different currencies. Pulling all of that into a single view—with accurate valuations, performance attribution, and exposure analysis—is genuinely hard, and doing it well requires sophisticated technology. The banks that have invested in this capability are delivering something their clients couldn't easily assemble on their own, and that's a real source of stickiness.
Digital onboarding has become another differentiator. Opening a private banking relationship used to involve weeks of paperwork, multiple in-person meetings, and a lot of waiting. The better platforms now handle much of this digitally, with secure document upload, electronic signatures, and identity verification that doesn't require a branch visit. For internationally mobile clients—executives relocating, families with multiple residences, entrepreneurs expanding into new markets—this is a meaningful improvement. Speed matters when a client is deciding between two institutions that both offer excellent service.
Security architecture has evolved alongside all of this. Biometric authentication, device binding, transaction monitoring, and encrypted communication are now table stakes rather than differentiators. But the best platforms go further, with granular permissions that let a family office control who sees what, and with audit trails that satisfy both internal compliance and external regulators. For clients who value privacy as much as they value returns, that architecture is a selling point, not a footnote.
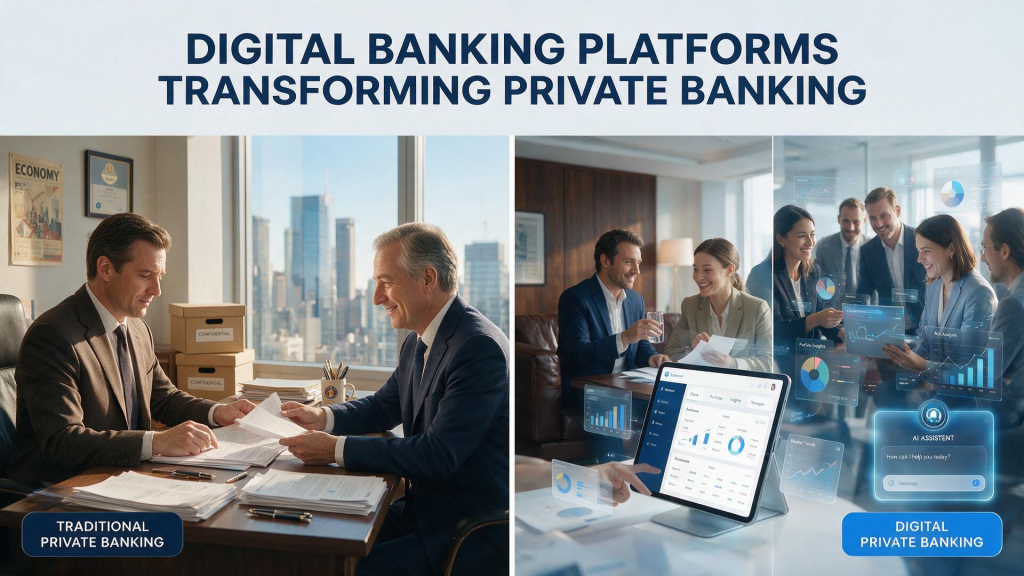
The Human Advisors Aren't Disappearing
Here's the part that gets lost in a lot of the commentary: digitization isn't replacing private bankers. It's freeing them. The relationship manager who used to spend half their week chasing statements and processing routine requests can now focus on the conversations that actually require judgment—estate structuring, tax planning, philanthropic strategy, the difficult conversations about family dynamics and succession. The technology handles the mechanics, and the human handles the meaning.
That division of labor is showing up in how the best online private banking services are designed. They're not trying to replace the advisor with an algorithm. They're giving the advisor better tools—dashboards that surface client needs before the client calls, alerts that flag unusual activity, collaborative planning tools that let the advisor and client work through scenarios together in real time. The result is a relationship that's both more responsive and more substantive, because the advisor isn't wasting time on logistics.
Clients seem to value this balance. Research consistently shows that high-net-worth individuals want digital convenience for routine tasks but still want a human relationship for complex decisions. They want to check their balance on their phone at midnight, but they want to talk to a person before they make a major move. The banks that have figured this out are the ones investing in both sides of the equation simultaneously, rather than assuming one will substitute for the other.
There's a generational dimension to this too. Younger heirs often expect a digital-first experience and may never develop the deep relationship their parents had with a particular banker. If the bank can't serve them digitally, they'll drift toward institutions that can. The digital wealth management capability becomes a retention tool for the next generation, not just a convenience for the current one. That's a strategic imperative, not a nice-to-have.
The Data Advantage and the Privacy Trade-Off
Every digital interaction generates data, and the banks that handle it well can turn that data into better advice. Understanding a client's spending patterns, cash flow needs, and liquidity requirements allows for more proactive recommendations. A banker who knows a client has a large tax payment coming up can suggest a short-term liquidity strategy before the client even asks. A platform that recognizes a client's concentration in a single stock can flag the risk and suggest diversification options before a market downturn forces the conversation.
But data also raises legitimate concerns, and the best platforms take them seriously. Clients need to understand what's being collected, how it's being used, and who has access to it. The banks that have built trust on this front tend to be explicit about their data practices and offer clients meaningful control over their information. That transparency is increasingly a differentiator, because high-net-worth clients are often the most attuned to privacy issues, and they're not shy about moving their business when they feel exposed.
The banking technology solutions underlying all of this are also evolving quickly. Cloud infrastructure, open APIs, and advanced analytics have made it possible for banks to build capabilities that would have been prohibitively expensive a decade ago. But the technology itself isn't the point. The point is what it enables: faster decisions, better advice, more reliable service. The banks that understand this distinction are the ones building platforms that actually improve the client experience, rather than just digitizing old processes and calling it innovation.
What to Watch as the Industry Matures
The next few years will separate the banks that have made real progress from the ones that have just made announcements. Watch for how the platforms handle complexity—a client with assets across multiple jurisdictions, entities, and currencies is a much better test than a single-account demo. Watch for whether the digital experience is genuinely integrated with the advisor relationship, or whether it's a separate app that clients use when their banker isn't available. Watch for whether the bank is investing in the security and compliance infrastructure that makes all of this sustainable.
Watch, too, for how these platforms handle the softer side of private banking. Can a client use the digital tools to schedule a call with their advisor? Can they share documents securely for a planning conversation? Can they see the history of advice and decisions in one place? These seem like small things, but they're the difference between a platform that supports the relationship and one that competes with it. The best private digital banking experiences make the advisor more accessible, not less.
There's also the question of how the industry will handle the transition from one generation to the next. Many private banking relationships are inherited along with the assets, and the digital platform is increasingly the vehicle through which the bank introduces itself to heirs. If that introduction feels like an outdated mobile app and a confusing login process, the relationship may not survive the handoff. The banks that have invested in a modern, intuitive experience are giving themselves a fighting chance to keep the next generation, and that's a bet that will pay off over decades.
The transformation of private banking isn't a story about technology replacing relationships. It's a story about technology making relationships work better—faster, more informed, more responsive. The banks that have embraced that story are already seeing the results in client retention, in referrals, and in the quality of conversations their advisors are having. The ones that haven't are going to find that the old model, however comfortable it once was, isn't enough anymore.
