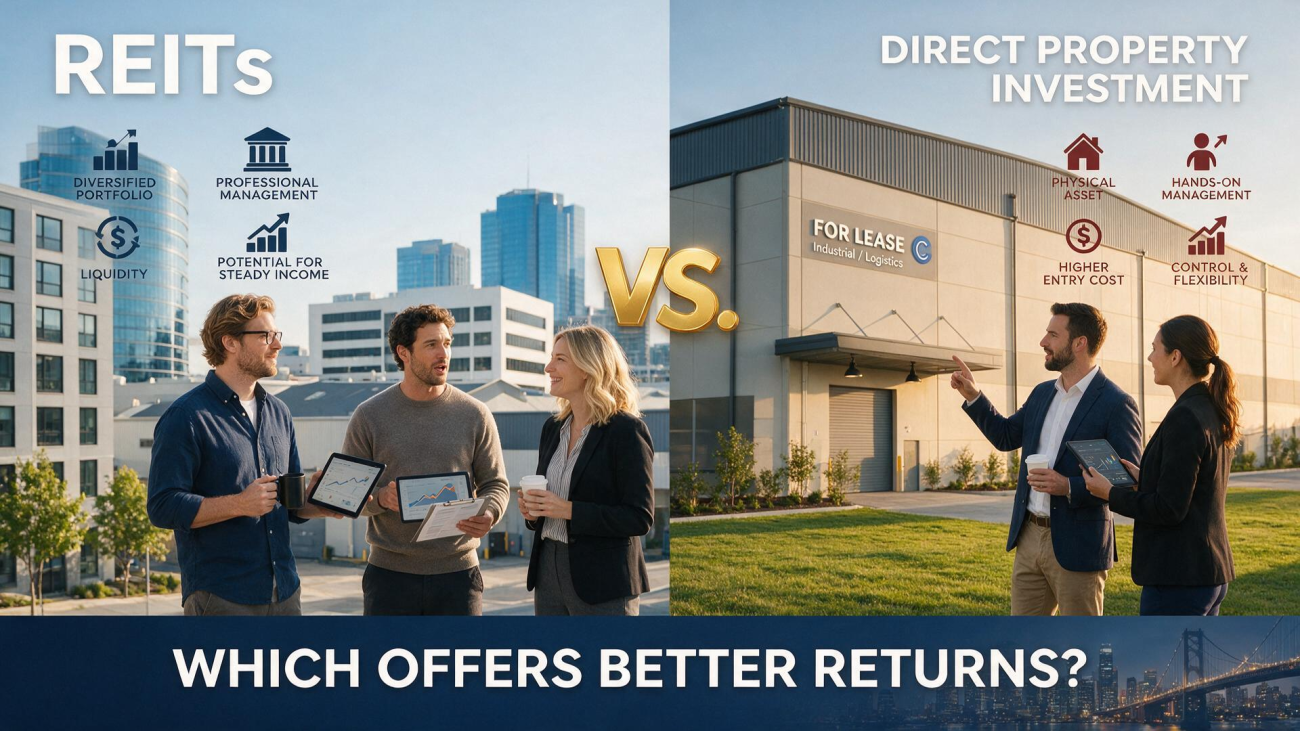
Two Ways to Own Real Estate, Two Very Different Experiences
Real estate has created more American fortunes than almost any other asset class, but the way people access it has changed dramatically over the past few decades. Historically, building wealth through property meant buying buildings—houses, apartments, office parks—and
managing them directly. That model still works, and it still produces some of the best returns available. But it requires capital, expertise, time, and a tolerance for illiquidity that not every investor has. REITs, or real estate investment trusts, offer a different path: the ability to own a diversified portfolio of income-producing real estate through a liquid, publicly traded security. The REITs vs real estate debate isn't about which one is better in the abstract. It's about which one fits your capital, your skills, your time horizon, and your tolerance for risk and illiquidity.The two approaches produce different return profiles, different tax treatments, and different levels of control. A direct property investor can use leverage to amplify returns, depreciate the
building for tax purposes, and make decisions about renovations and tenant selection that directly affect the property's value. A REIT investment offers diversification, liquidity, and professional management, but it also comes with less control and a different tax structure. Understanding those trade-offs is the first step toward choosing the right approach for your situation.What makes this particularly relevant right now is that the real estate market is in a period of transition. Interest rates have risen, which affects both the cost of financing for direct investors and the valuation of REITs. Certain property sectors—office, retail—are facing structural challenges, while others—industrial, data centers, residential—are benefiting from long-term trends. The direct property investment that worked a decade ago may not work as well today, and the REITs that are positioned in the right sectors may offer better returns than the properties that are struggling.
How REITs Work and What They Offer
A REIT is a company that owns, operates, or finances income-producing real estate. To qualify as a REIT under the tax code, the company must distribute at least 90% of its taxable income to shareholders as dividends, which is why REITs are known for their high yields. That structure eliminates the corporate-level tax, which means the income flows through to shareholders more efficiently than it would in a traditional corporation. The real estate investment trusts that investors buy are typically publicly traded, which means they offer daily liquidity that direct property ownership can't match.
The diversification benefit is one of the strongest arguments for REITs. A single REIT might own hundreds of properties across multiple markets and property types, which means a small investment gives you exposure that would be impossible to replicate with direct ownership unless you had millions of dollars to deploy. A portfolio of REITs can be diversified across sectors—residential, industrial, retail, office, healthcare, data centers—and across geographies, which reduces the risk that any single property or market will drag down your returns. The real estate portfolio diversification that REITs provide is one of their most valuable features, especially for investors with limited capital.
Liquidity is the second major advantage. Direct property takes months to sell, and in a downturn, it may be impossible to sell at any reasonable price. REITs can be bought and sold in seconds, which means you can adjust your allocation quickly if your circumstances change or if you see a better opportunity. That liquidity comes with a cost—REIT prices can be volatile, and they don't always reflect the underlying value of the properties—but for many investors, the ability to access their capital is worth the trade-off. The REIT investment returns that investors earn include both the dividend income and the price appreciation, and the liquidity makes it easier to capture both.
Professional management is the third advantage. REITs are managed by teams of real estate professionals who have expertise in acquisitions, property management, financing, and dispositions. For investors who don't have the time or the expertise to manage properties themselves, that professional management is a significant benefit. The real estate investment trusts that perform well over time are the ones with strong management teams that can navigate market cycles and allocate capital effectively.
How Direct Property Investment Works
Direct property investment is the traditional path to real estate wealth, and it offers advantages that REITs can't replicate. The first is control. When you own a property directly, you decide who rents it, how much to charge, when to renovate, and when to sell. That control allows you to add value in ways that a REIT shareholder can't—by improving the property, repositioning it to a higher and better use, or selecting tenants who will enhance the property's value. The direct property investment that produces the best returns is often the one where the investor is actively involved in managing and improving the asset.
Leverage is the second advantage. Direct property investors can use mortgage financing to amplify their returns, often at loan-to-value ratios of 70% to 80% or more. That leverage magnifies both the gains and the losses, but when used responsibly, it can significantly boost the return on equity. A property that appreciates 5% with 75% leverage produces a 20% return on the investor's equity, which is far higher than the unlevered return. The real estate investment returns that direct investors earn are often driven by that leverage, which is one of the reasons direct property has historically outperformed REITs for investors who can access it.
Tax advantages are the third benefit. Direct property investors can depreciate the building for tax purposes, which reduces their taxable income even if the property is generating cash flow. They can also use 1031 exchanges to defer capital gains taxes when they sell, which allows them to roll the proceeds into a new property without paying tax. Those tax advantages can significantly increase the after-tax returns of direct property investment, especially for high-income investors in high tax brackets. The REITs vs real estate comparison has to account for those tax differences, because they can be substantial over time.
The disadvantages of direct property are equally significant. It's illiquid, it requires active management, it concentrates risk in a single property or a small number of properties, and it requires significant capital to get started. A single vacancy, a major repair, or a problem tenant can wipe out a year's return, and a downturn in the local market can leave the investor with a property that can't be sold. The direct property investment that works is the one where the investor has the capital, the expertise, and the tolerance for those risks, and where the property is part of a diversified portfolio rather than the whole of it.
Comparing Returns: What the Data Shows
The historical data on REITs versus direct property is mixed, and the comparison depends heavily on the time period, the leverage used, and the specific properties involved. Over the long term, both have produced solid returns, but the return profiles are different. REITs have historically delivered returns that are comparable to or slightly lower than direct property, but with much lower volatility and much higher liquidity. Direct property has delivered higher returns for investors who use leverage and actively manage the assets, but with much higher risk and much lower liquidity.
The REIT investment returns are driven by the dividend yield, the growth in funds from operations, and the change in the valuation multiple. In periods when REITs are trading at a discount to their net asset value, the returns can be strong as the discount closes. In periods when they're trading at a premium, the returns can be weak as the premium compresses. That valuation dynamic is one of the reasons REIT returns can be volatile in the short term, even though the underlying properties are stable.
The direct property investment returns are driven by the income the property produces, the appreciation in its value, and the tax benefits of ownership. Those returns are less volatile than REIT returns, because the property isn't priced daily and the income is relatively stable. But the returns are also less liquid, and the investor can't easily adjust their allocation if the market changes. The direct investor is committing capital to a specific property in a specific market, which means the returns depend heavily on the performance of that property and that market.
It's also worth considering the role of fees. REITs charge management fees, which reduce the returns that flow through to shareholders. Direct property investment also has costs—property management fees, maintenance, insurance, taxes—but those costs are more visible and more controllable. The real estate portfolio diversification that REITs provide comes at a cost, and investors should compare the net returns after all fees, not just the gross returns.
Choosing the Right Approach for Your Situation
The choice between REITs and direct property depends on several factors. The first is capital. Direct property requires a significant down payment, closing costs, and reserves for maintenance and vacancies. REITs can be purchased with a small amount of capital, which makes them accessible to investors who don't have the resources for direct ownership. The REITs vs real estate decision often comes down to how much capital you have and how much you're willing to commit to a single asset.
The second factor is time and expertise. Direct property requires active management, or at least the willingness to hire and oversee a property manager. REITs are passive, which means you can invest without any involvement in the day-to-day operations. The real estate investment trusts that work for passive investors are the ones that provide professional management and diversification without requiring any effort from the investor. If you don't have the time or the interest to manage properties, REITs are the better choice.
The third factor is liquidity. If you might need to access your capital in the next few years, REITs are the better choice because they can be sold quickly. Direct property is illiquid, and selling it takes months and involves significant transaction costs. The direct property investment that works is the one where the investor doesn't need the capital for the foreseeable future, and where the property can be held through a downturn.
The fourth factor is tax situation. Direct property offers depreciation and 1031 exchange benefits that REITs don't, which can significantly increase after-tax returns for high-income investors. REIT dividends are taxed as ordinary income, which is the highest rate for most investors, though a portion may qualify for the 20% pass-through deduction. The REIT investment returns that matter are the after-tax returns, and for investors in high tax brackets, the tax advantages of direct property can be substantial.
A Blended Approach That Captures Both
For many investors, the best approach isn't choosing between REITs and direct property—it's using both. A portfolio that includes a core allocation to REITs for diversification and liquidity, plus a satellite allocation to direct properties for control and tax benefits, can capture the advantages of both approaches while mitigating the disadvantages of each. The real estate portfolio diversification that a blended approach provides is more robust than either approach alone.
The specific allocation depends on the investor's goals and resources. An investor with significant capital and a desire to be hands-on might allocate 60% to direct property and 40% to REITs. An investor with less capital and a preference for passivity might allocate 80% to REITs and 20% to a direct property or a real estate fund. The REITs vs real estate decision doesn't have to be binary—it can be a blend that fits the investor's specific situation.
It's also worth considering real estate debt as a complement to both. Lending against real estate, either through mortgage REITs or private credit funds, can provide income with a different risk profile than owning equity. Debt investments are typically senior in the capital structure, which means they're paid first if something goes wrong. The real estate investment returns that a blended portfolio can achieve are more stable and more predictable than those of a concentrated approach.
Finally, remember that real estate is a long-term asset class, regardless of how you access it. The investors who build wealth through real estate are the ones who think in decades, not months. Whether you choose REITs, direct property, or a blend of both, the key is to be patient, diversified, and disciplined. The REIT investment returns and direct property investment returns that compound over decades are what build wealth, not the returns in any single year. Choose the approach that fits your situation, and stick with it through the cycles.
