Why Real Estate Still Builds Wealth—If You Diversify It Properly
Real estate has been one of the most reliable paths to wealth in American history, but the way most people build it is unnecessarily risky. They buy a few rental properties in their
own city, concentrate their capital in a single market, and expose themselves to the ups and downs of one local economy. That's not a portfolio. It's a concentrated bet with property attached. A real estate investment portfolio is something different: a deliberately diversified collection of properties and property-related assets that spreads risk across geographies, property types, and economic cycles. Building one takes more thought than buying the duplex down the street, but the result is a more resilient and more predictable path to long-term wealth.The case for real estate is well understood. It generates income, it tends to appreciate over time, it provides a hedge against inflation, and it offers tax advantages that are hard to replicate with other assets. The problem
is that those benefits come with risks that are easy to underestimate. A single vacancy in a small portfolio can wipe out a year's return. A local downturn can leave you with properties you can't rent and can't sell. A major repair can consume years of savings. The diversified real estate investments that work are the ones that reduce those risks without sacrificing the benefits, and that requires a more deliberate approach than most investors take.What makes this particularly important right now is that the real estate market has changed. Interest rates are higher than they were a few years ago, which affects both the cost of financing and the attractiveness of certain property types. The pandemic shifted demand patterns between cities and suburbs, and those shifts are still working their way through the market. The property investment strategies that worked a decade ago may not work as well today, which is why a diversified approach is more valuable than ever.
Why Concentration Is the Biggest Risk
The biggest mistake real estate investors make is concentrating their capital in a single market, a single property type, or a single tenant. That concentration feels safe when things are going well, because the returns are visible and the risks seem abstract. But the risks are real, and they can materialize quickly. A major employer closes a plant, and suddenly the demand for rental housing in that town collapses. A retail sector struggles, and the strip mall you own loses its anchor tenant. A hurricane hits, and the properties you own in that region sustain damage that insurance doesn't fully cover.
The problem is that real estate is inherently local. The value of a property depends on the local economy, the local job market, the local population trends, and the local regulations. Those factors can diverge dramatically from the national trends. A city that's booming nationally might have neighborhoods that are declining, and a city that's struggling nationally might have submarkets that are thriving. The real estate portfolio management that works recognizes that local variation and diversifies across it, rather than assuming that a rising tide lifts all boats.
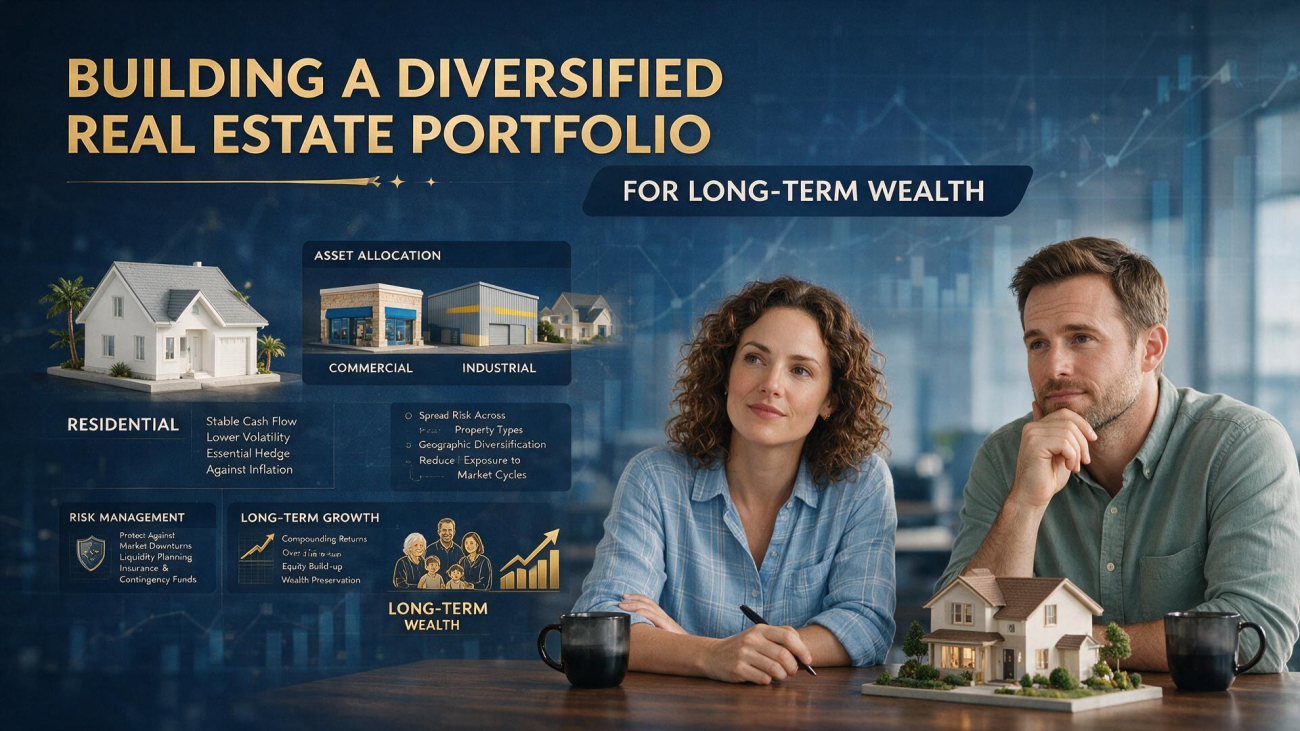
Diversification isn't just about geography. It's also about property type. Residential rentals behave differently from commercial office space, which behaves differently from industrial warehouses, which behaves differently from retail. Those differences can be a source of stability, because when one sector is struggling, another may be holding up. A portfolio that includes residential, commercial, and industrial properties is more resilient than one that's concentrated in a single type. The real estate wealth building that works uses that diversification to smooth out the returns over time.
Tenant diversification matters too. A single-tenant property, like a building leased to one large company, is riskier than a multi-tenant property, because the loss of that tenant means the loss of all the income. A portfolio that includes both single-tenant and multi-tenant properties, and that has a mix of lease expiration dates, is more resilient than one that depends on a handful of tenants. The diversified real estate investments that work spread the risk across many tenants, not just many properties.
The Vehicles Available to Individual Investors
Not long ago, diversifying a real estate portfolio was impractical for most individual investors. Buying properties in multiple markets required local expertise, significant capital, and hands-on management. That's changed. Today, there are more ways to access real estate than ever, and the right mix depends on the investor's capital, experience, and tolerance for illiquidity. The property investment strategies that work for a high-net-worth investor are different from those that work for someone just starting out.
Direct ownership is the traditional approach. Buying rental properties gives you control over the asset, the ability to use leverage, and the tax benefits of depreciation. It also requires active management, local market knowledge, and the capital to handle vacancies and repairs. Direct ownership is a good fit for investors who want to be hands-on and who have the resources to diversify across multiple properties. The real estate investment portfolio that includes direct ownership needs to be large enough to spread the risk across properties, or it's not really diversified.
Real estate investment trusts, or REITs, offer a different approach. REITs are publicly traded companies that own and operate income-producing real estate. They give you instant diversification across property types and geographies, with the liquidity of a stock. They also have a tax structure that requires them to distribute most of their income to shareholders, which makes them attractive for income-oriented investors. The real estate portfolio management that uses REITs can build a diversified allocation with a fraction of the capital required for direct ownership, and with far more liquidity.
Real estate syndications and private funds are a third option. These vehicles pool capital from multiple investors to acquire properties that would be too large or too expensive for any one investor to buy alone. They offer access to institutional-quality properties and professional management, but they also come with higher fees, less liquidity, and less control. The real estate wealth building that uses syndications and private funds needs to evaluate the sponsor's track record, the fee structure, and the specific property's risk profile, rather than assuming that professional management guarantees good returns.
It's also worth considering real estate debt as a complement to equity. Lending against real estate, either through mortgage REITs or private credit funds, can provide income with a different risk profile than owning the property. Debt investments are typically senior in the capital structure, which means they're paid first if something goes wrong. The diversified real estate investments that work often include both equity and debt, because the two behave differently in different market conditions.
Building an Allocation That Balances Risk and Return
The right allocation to real estate depends on the investor's overall portfolio, their goals, and their tolerance for illiquidity. For most high-net-worth investors, real estate is a component of a broader portfolio, not the whole thing. A common range is 10% to 30% of total assets, with the exact number depending on the investor's situation. The real estate investment portfolio that works is the one that's sized appropriately to the investor's overall financial plan, not the one that's maximized for real estate exposure.
Within the real estate allocation, diversification across property types is essential. Residential, commercial, industrial, and retail each have different risk and return characteristics, and they respond differently to economic conditions. A portfolio that's heavy in office space might struggle as remote work reduces demand, while a portfolio that's heavy in industrial warehouses might benefit from the growth of e-commerce. The property investment strategies that work for a diversified portfolio include exposure to multiple property types, rather than a concentrated bet on one sector.
Geographic diversification matters as much as property type. Different regions have different economic drivers, different population trends, and different regulatory environments. A portfolio that's concentrated in one city or one region is vulnerable to a local downturn that wouldn't affect a more diversified portfolio. The real estate portfolio management that works spreads the risk across regions, rather than assuming that the investor's home market is representative of the broader economy.
It's also worth considering the role of leverage. Real estate investors often use debt to amplify returns, and leverage can be a powerful tool when used responsibly. But leverage also amplifies losses, and it introduces the risk of forced selling if the property's value declines and the lender demands repayment. The real estate wealth building that works uses leverage conservatively, with enough equity cushion to absorb a decline in value without triggering a crisis. The goal isn't to maximize returns; it's to build wealth steadily over time.
Managing the Portfolio Over Time
A real estate portfolio isn't something you set up and forget. Properties need to be maintained, tenants need to be managed, and the market needs to be monitored. The real estate portfolio management that works includes a plan for ongoing oversight, whether that's through professional property management, a dedicated staff, or a hands-on owner. Without that oversight, the portfolio can deteriorate, and the returns can disappear.
It's also worth reviewing the allocation periodically. The performance of different property types and regions will cause the allocation to drift over time, and rebalancing keeps the risk profile consistent. A portfolio that was 30% commercial and 70% residential might become 40% commercial and 60% residential after a commercial property appreciates. The diversified real estate investments that work are the ones that are rebalanced regularly, not the ones that are left to drift.
And it's worth planning for the tax implications. Real estate has significant tax advantages, including depreciation, 1031 exchanges, and preferential capital gains rates. Those advantages can be substantial, but they require planning to capture. The real estate investment portfolio that works is the one that's structured with taxes in mind, not the one that treats taxes as an afterthought. Working with a tax advisor who understands real estate is essential for maximizing the after-tax returns.
Finally, remember that real estate is a long-term asset. It's not liquid, it's not fast, and it's not exciting. The investors who build wealth through real estate are the ones who think in decades, not months. The property investment strategies that work are patient and disciplined, focused on steady income and long-term appreciation rather than quick gains. That's not glamorous, but it's effective, and it's the path to long-term wealth that real estate has always offered.
